
Is Now a Good Time to Buy a House in Ontario?

HOMEH Publishing Department
Editorial team · HOMEH Inc., Brokerage · RECO #6000380 Jan 27, 2024 5 min read
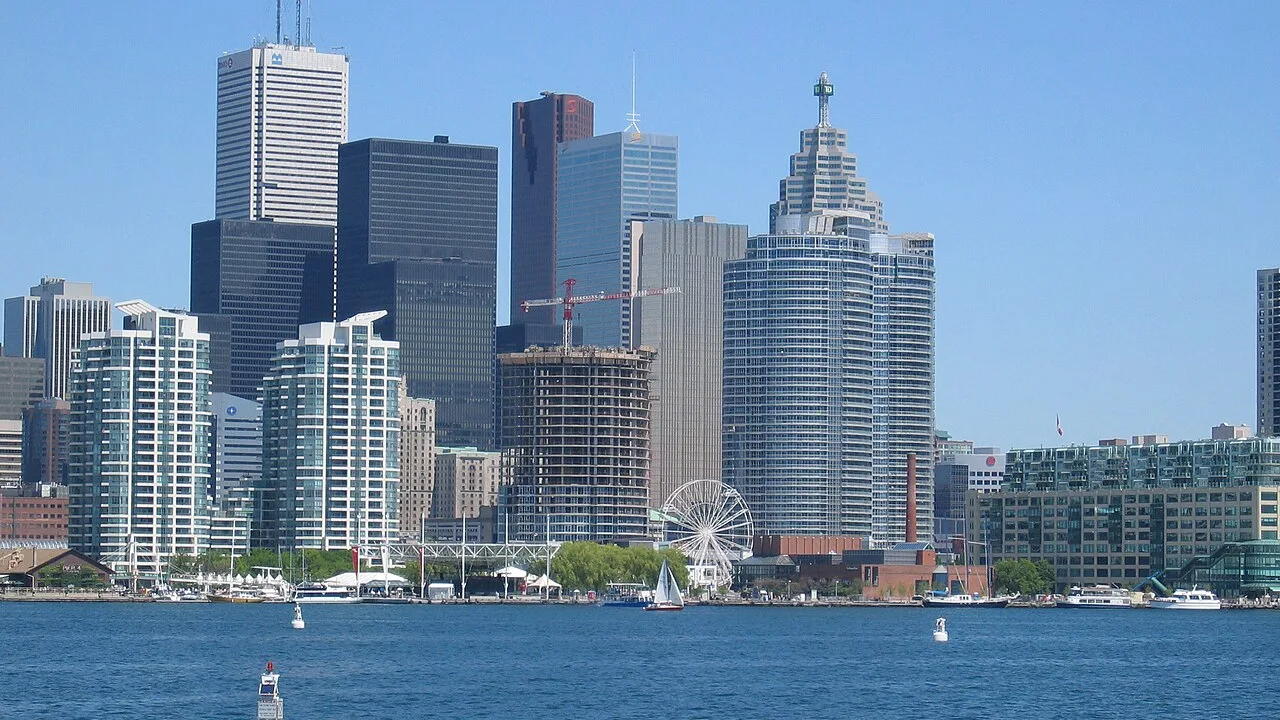
"Should I buy now or wait?" is the most common question in Ontario real estate — and the most misunderstood. The truth is that your readiness matters more than market timing. Trying to call the bottom is a losing game; building a purchase you can comfortably afford is not. This guide gives you a practical framework to decide, using only facts you can verify today.
 Key takeaways
- Personal readiness — stable income, a solid down payment, manageable debt — matters more than timing the market.
- You must pass the mortgage stress test: the greater of your rate + 2% or 5.25%.
- Aim to keep housing costs within roughly 39% of gross income (GDS) and all debts within 44% (TDS).
- First-time buyer programs (FHSA, RRSP HBP, LTT rebates) can meaningfully lower your entry cost.
- Check live local conditions on HOMEH Market Watch rather than reacting to national headlines.
Stop trying to time the market
Waiting for the "perfect" moment usually backfires. Nobody can reliably predict where prices go next — that depends on interest rates, supply and demand interacting in ways no forecaster controls (we cover this in the Ontario housing market outlook). What you can control is whether you're financially ready to buy a home you can keep through ups and downs.

The readiness checklist
Before market conditions even enter the picture, run yourself through this list. If you can tick most boxes, you're in a strong position regardless of what the headlines say.
- Stable income you expect to continue for the foreseeable future.
- A sufficient down payment — at least 5% on the first $500,000 of price, more above that.
- Manageable debt so you fit within lender ratios.
- A closing-cost cushion of roughly 1.5%–4% of the price on top of your down payment.
- Plans to stay put long enough to ride out short-term swings.
Not sure about the down payment? Our guide to how much down payment you need in Ontario breaks down the tiers.
Can you actually qualify?
Affordability isn't just your comfort level — lenders apply hard rules. Two ratios and the stress test decide what you can borrow.
The stress test means you must prove you could handle payments at a rate well above today's contract rate. Run your scenario through the stress-test calculator and find your ceiling with the affordability calculator.
Down payment tiers in Ontario
How much you need up front scales with price. Here are the minimums you'll work from:
| Purchase price | Minimum down payment |
|---|---|
| Under $500,000 | 5% |
| $500,000 – $1,499,999 | 5% on first $500k + 10% on the rest |
| $1,500,000 or more | 20% (cannot be insured) |
Since December 15, 2024, the insured-mortgage cap rose to $1.5 million and 30-year amortizations are available to first-time buyers and buyers of new builds — both can make a purchase more attainable.
Use the programs built for you
First-time buyers have powerful tools to lower the cost of getting in. These don't depend on market timing at all — they're available now:
- FHSA — contribute up to $8,000/year ($40,000 lifetime); contributions are tax-deductible and qualifying withdrawals are tax-free.
- RRSP Home Buyers' Plan — withdraw up to $60,000 per person ($120,000 per couple) tax-free, repaid over 15 years.
- Land transfer tax rebates — up to $4,000 provincial, plus up to $4,475 municipal in Toronto.
See the full menu in first-time home buyer programs in Canada.
So — is now the time?
If you're financially ready, qualify comfortably, and plan to stay put, then your good time to buy is when you're prepared — not when a pundit declares the market "good." If you're not ready, use the wait to save, reduce debt, and improve your position. Either way, base the decision on live local data, not headlines.

Frequently asked questions
Is it better to buy now or wait for prices to drop?
How do I know if I can afford to buy?
What's the minimum down payment in Ontario?
Where can I check current market conditions?
Ready to put this into action?
Get pre-qualified in five minutes, or talk to a HOMEH advisor — no credit pull, no commitment.
Keep reading.
Buying & Selling
Should You Buy or Sell First? How to Decide
Selling a Home
When Is the Best Time to Sell a House in Ontario?
Market & Investing
