
Ontario Housing Market Outlook

HOMEH Publishing Department
Editorial team · HOMEH Inc., Brokerage · RECO #6000380 Jan 23, 2024 6 min read
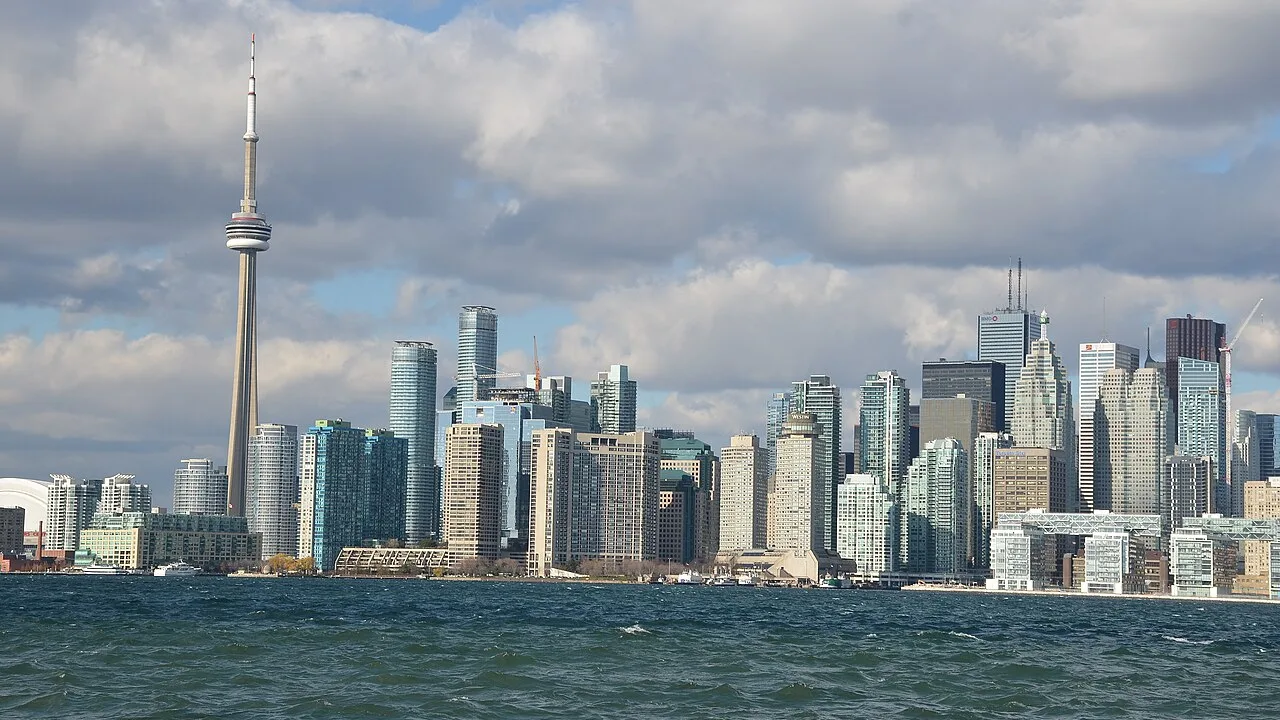
Everyone wants to know one thing about the Ontario housing market: which way are prices heading? The honest answer is that nobody can reliably forecast a specific price. What you can do is understand the three forces that actually move the market — interest rates, housing supply, and buyer demand — and then watch live data instead of headlines. This guide explains those drivers in plain English and shows you where to find the real numbers.
 Key takeaways
- No one can credibly predict exact future prices — focus on the drivers, not the forecasts.
- The Bank of Canada's policy rate is the single biggest lever on borrowing costs and demand.
- Supply (new construction and resale inventory) and population-driven demand set the longer-term direction.
- Government rules — like the $1.5M insured-mortgage cap and 30-year amortizations for first-time buyers — shape who can buy.
- Track live, local data through HOMEH Market Watch rather than relying on national averages.
Why nobody can predict prices (and what to do instead)
Housing prices are the product of millions of individual decisions, interest-rate moves no one fully controls, and policy changes that arrive with little warning. Anyone promising a precise number for next year is guessing. The smarter approach is to understand the levers that genuinely shift the market, then monitor them as they change.
Think of it like weather: you can't say it will rain at 3 p.m. next Tuesday, but you can read the pressure systems. In real estate, the three big systems are rates, supply, and demand. For the live local picture, use the HOMEH Market Watch tool instead of generic headlines.
Driver 1: Interest rates
Borrowing costs are the most powerful short-term driver. When the Bank of Canada changes its policy rate, variable mortgage rates and lender pricing follow, which changes how much buyers can afford. Lower rates expand budgets and tend to add competition; higher rates do the opposite.

Driver 2: Supply
Supply has two parts: new homes being built and existing homes listed for resale. When inventory is tight relative to buyers, sellers gain pricing power; when listings pile up, buyers do. Ontario's long-running challenge has been building enough homes to match population growth, which keeps structural pressure on supply.
Recent federal rules aim to ease the squeeze on new construction. Since December 15, 2024, the insured-mortgage cap rose to $1.5 million and 30-year amortizations became available to first-time buyers and buyers of new builds — both designed to help more people purchase, especially newly built homes. For research on national supply trends, see CMHC.
Driver 3: Demand
Demand reflects how many people want to buy and whether they can. Population growth, employment, household formation, and confidence all feed into it — and affordability tools either unlock or restrain it. The first-time buyer programs below directly affect demand by lowering the cash hurdle to entry.
If you're entering the market for the first time, our first-time home buyer guide for Ontario walks through every program and how they stack.
How the drivers interact
These forces rarely move in isolation. Falling rates can boost demand faster than supply can respond, tightening the market; a wave of new completions can soften it even when rates are steady. That's why a single national average tells you little about your specific city or neighbourhood.
| Driver | When it eases | When it tightens |
|---|---|---|
| Interest rates | Rates fall, budgets grow | Rates rise, budgets shrink |
| Supply | More listings / new builds | Few listings, slow building |
| Demand | Strong jobs & population | Weak confidence or affordability |

What this means for buyers and sellers
For buyers, the takeaway is to focus on what you control: your budget, your timing flexibility, and your costs. For sellers, it's pricing to the live market and minimizing what the sale costs you. Investors should run the numbers cold — start with how to invest in real estate in Canada and understanding real estate market cycles.

Frequently asked questions
Will house prices in Ontario go up or down?
What is the biggest factor affecting the housing market?
How do government rules affect the market?
Where can I see live Ontario market data?
Ready to put this into action?
Get pre-qualified in five minutes, or talk to a HOMEH advisor — no credit pull, no commitment.
Keep reading.
Market & Investing
How to Read Housing Market Data (Like Sales-to-Listings)
Market & Investing
Understanding the Toronto Condo Market
Market Reports
