Buying a Pre-Construction Condo in Ontario: Pros, Cons & Costs

HOMEH Publishing Department
Author Feb 07, 2023 6 min read
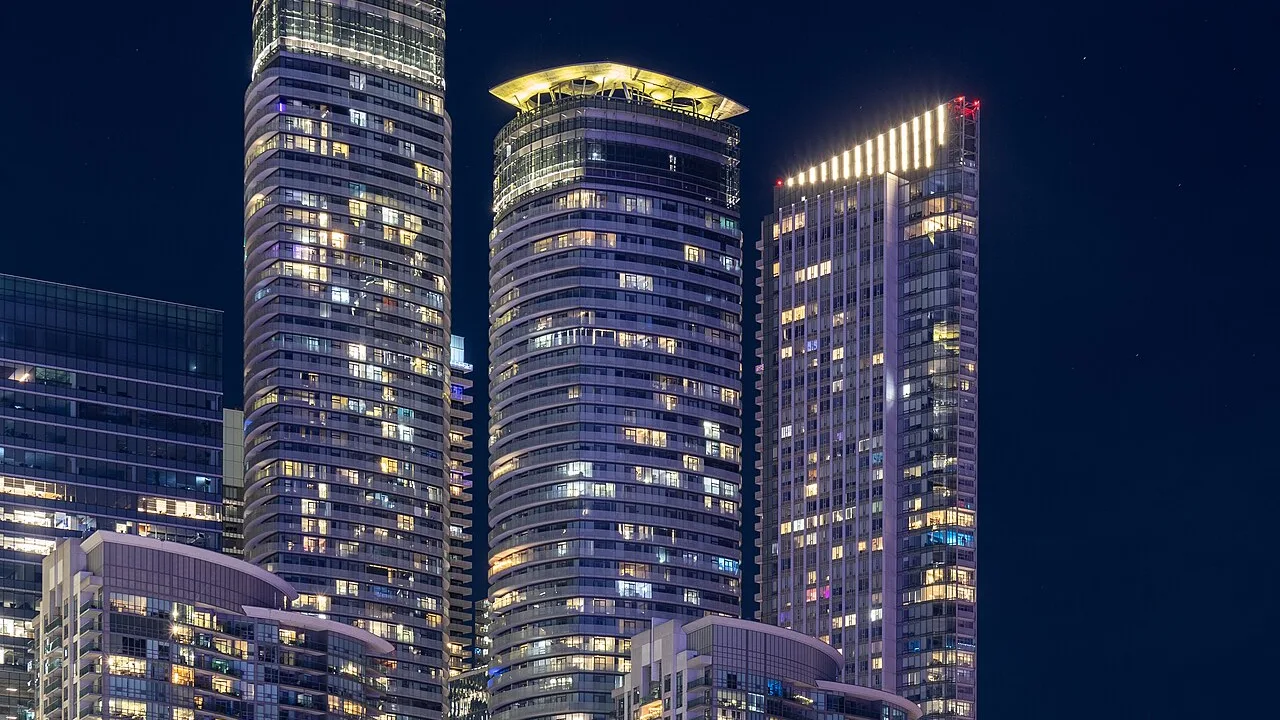
A pre-construction condo lets you lock in today's price for a unit that may not exist for years — and walk in with brand-new everything. But you're buying from a floor plan, paying staged deposits, and facing costs that resale buyers never see. Here's an honest look at the pros, cons and real numbers of buying pre-construction in Ontario.
 Key takeaways
- You buy from plans and renderings, with occupancy often years away.
- Deposits are paid in stages and typically total 15%–20% of the price.
- A 10-day statutory cooling-off period lets you cancel a new condo agreement.
- Watch for occupancy fees, closing-cost adjustments, and HST treatment.
- New homes may qualify for the First-Time Buyer GST rebate of up to $50,000.
What 'pre-construction' actually means
A pre-construction (or 'pre-con') condo is sold before — or while — it's being built. You sign an agreement of purchase and sale based on floor plans, renderings and a feature sheet, then wait through construction until the building is ready for occupancy and, later, final closing.
The appeal is straightforward: you pick your unit early, customize finishes, and lock in a price you hope the market will exceed by the time you move in. The trade-off is uncertainty — timelines slip, and what you see in the sales centre isn't always what gets built.

How the deposits work
Unlike a resale purchase, pre-construction deposits are paid in instalments over the construction period. A common structure totals around 15%–20% of the purchase price spread across several payments.
Because deposits are staged, planning your down payment savings around the builder's milestone dates matters. Note that Ontario's minimum-down-payment rules still apply at final closing: 5% on the first $500,000 and 10% on the portion above.
The hidden costs resale buyers don't face
Pre-construction has a longer list of extra costs than a resale purchase. Read the agreement carefully — many of these are negotiable caps.
- Occupancy fees — a monthly 'phantom rent' paid between occupancy and final closing, when you can live in the unit but don't yet own title.
- Development charge adjustments — municipal levies passed on at closing; cap these in your agreement.
- Assignment and levy fees if you sell before closing.
- HST — new homes are subject to HST, though rebates may apply.
- Standard closing costs — legal fees, land transfer tax and more.

Taxes, rebates and financing
New homes carry HST, but Ontario and federal rebates soften the blow. Notably, the First-Time Home Buyers' GST/HST Rebate can be worth up to $50,000: full GST is removed on qualifying new homes valued up to $1,000,000 and phased out between $1M and $1.5M, for agreements signed on or after May 27, 2025. See our deep dive on the GST rebate on new homes.
Financing is also different: lenders won't fund the deal until close to final closing, and rules may have changed by then. Since December 15, 2024, the insured mortgage cap is $1.5M and 30-year amortizations are allowed for first-time buyers and buyers of new builds — a meaningful perk for pre-con purchasers. Learn the broader picture in our guide to how mortgages work in Canada and the full guide to buying a house in Ontario.

Is pre-construction right for you?
Pre-construction suits buyers who don't need to move immediately, have flexible savings for staged deposits, and want a brand-new unit with warranty coverage. It's riskier for buyers on tight timelines or those who need certainty on price and possession.
If you're weighing it as an investment, compare the trade-offs in our piece on pre-construction vs resale, and check your numbers with the affordability calculator before committing.
Frequently asked questions
Can I cancel a pre-construction condo purchase?
How much deposit do I need for a pre-construction condo?
What are occupancy fees?
Do I pay HST on a new condo?
Is buying pre-construction a good investment?
Ready to put this into action?
Get pre-qualified in five minutes, or talk to a HOMEH advisor — no credit pull, no commitment.